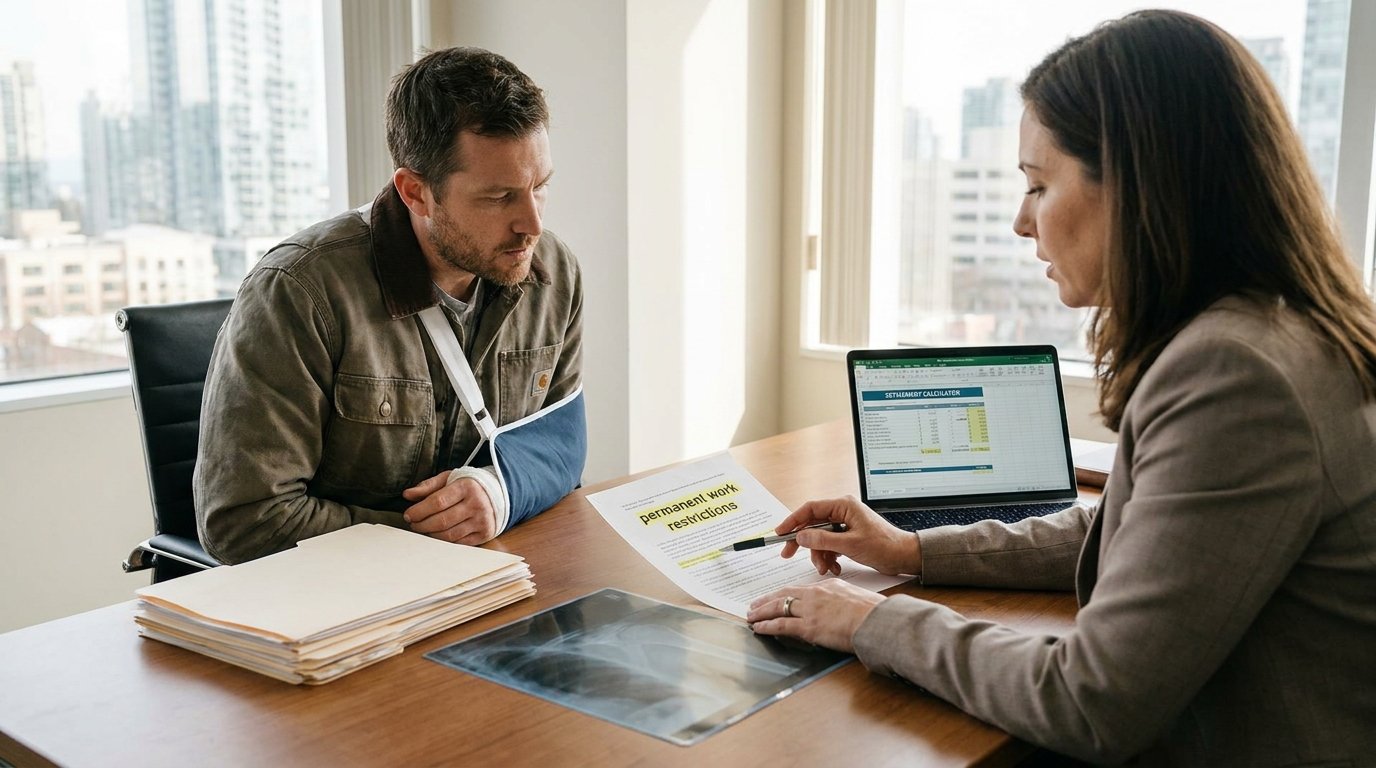
If your doctor just told you that your work restrictions are now permanent, one question probably comes to mind right away: does permanent work restriction increase the settlement in a workers’ compensation case? For most people, the short answer is yes — but not automatically, and not by the same amount every time.
A permanent work restriction is a lasting limit a doctor places on what you can do at work after a job injury, such as no lifting over a certain weight, no repeated bending, or no long periods of standing. Once these limits are called “permanent,” your case usually shifts from a short-term wage-replacement claim into a bigger conversation about long-term disability and lost future income. That shift is exactly why settlement numbers tend to move once permanent restrictions are on the record.
This guide breaks down how permanent restrictions actually change settlement value, when they don’t move the number much, and what tends to make the biggest difference in 2026.
Quick Facts
| Question | Short Answer |
|---|---|
| Does it usually raise the settlement? | Yes, in most cases, but the size of the increase varies by state and job type |
| What matters most? | Whether the restriction stops you from returning to your old job or old pay |
| Main legal terms involved | Maximum medical improvement (MMI), permanent partial disability (PPD), loss of earning capacity |
| Typical settlement range (general, 2026 data) | Roughly $20,000–$50,000 for many claims; permanent total disability cases can reach $200,000 or more |
| Biggest state factor | Whether the state uses an impairment-rating system, a wage-loss system, or both |
What Counts as a Permanent Work Restriction
A permanent work restriction is different from a temporary one. Temporary restrictions apply while you’re still healing. Permanent restrictions are assigned after you reach maximum medical improvement (MMI) — the point where a doctor decides your condition has stabilized and further treatment won’t meaningfully improve it. At that stage, if lasting limits remain, they become part of your permanent medical record and your workers’ comp file.
Common examples include weight-lifting limits, restrictions on standing, kneeling, or climbing, limits on repetitive motion, or a total ban on returning to a specific type of physical labor. Back injuries are one of the most common sources of these lasting restrictions, and the calculation can shift noticeably depending on where you live — for a closer look at how one state handles this, see this breakdown of workers’ comp back injury settlements in Florida.
Why Permanent Restrictions Usually Raise the Settlement Value
Permanent restrictions tend to increase settlement value for a few connected reasons.
They prove lasting disability. Once a doctor states restrictions are permanent, it becomes harder for an insurance company to argue the injury was minor or fully resolved. This documentation is often the strongest evidence in the case.
They support a loss-of-earning-capacity claim. Many states calculate part of a settlement based on how much your ability to earn money has dropped because of the injury, not only your medical impairment percentage. A worker who can no longer lift more than ten pounds may be locked out of an entire trade, which is treated as a serious, lasting financial loss.
They can block a return to your old job or industry. If restrictions mean you cannot go back to your pre-injury employer or field at all, insurers generally have to account for the cost of retraining, lower future wages, or long-term wage-loss benefits.
They feed directly into your disability rating. In states that use an impairment-based system, doctors reference the restrictions when assigning a percentage disability rating. That rating is usually multiplied by a set number of weeks of benefits and your compensation rate, so a higher rating tends to mean a higher payout.
When Permanent Restrictions Don’t Move the Number Much
It’s a mistake to assume every permanent restriction automatically means a bigger check. What actually matters is the practical effect of the restriction, not just the fact that a doctor wrote one down.
If the restriction doesn’t change your actual job duties, your pay, or your ability to do the same work — for example, a desk-job worker given a minor lifting restriction that never applies to their daily tasks — the settlement impact may be small. Insurance adjusters will often look closely at whether the restriction truly forced a job change, a pay cut, or a career change before agreeing to a higher number. This is one of the more overlooked parts of these cases, since many people assume the restriction alone guarantees a bigger settlement rather than what it actually does to their earning ability.
How States Calculate This Differently
Workers’ comp is state-by-state, and the exact method for turning a permanent restriction into a dollar figure varies quite a bit.
- Impairment-based states (including many scheduled-injury systems) rely heavily on a medical disability percentage tied to the injured body part.
- Loss-of-earning-capacity states, used in roughly a dozen states, calculate benefits based on the actual gap between pre-injury and post-injury earning ability, factoring in age, education, and job history.
- Mixed systems, common in states like California, combine a medical impairment rating with adjustments for age and job demands to set the final disability rating and payout.
- Several states, including Virginia and Pennsylvania, treat a documented inability to return to the pre-injury job as one of the clearest paths to a higher settlement, since it directly supports the wage-loss argument.
Because of these differences, the same injury and the same restriction can settle for very different amounts depending on where the claim is filed.
Typical Settlement Ranges in 2026
Exact numbers vary widely by state, injury, and job, so treat these as general ranges rather than a promise. Many standard workers’ comp claims settle somewhere between $20,000 and $50,000. Cases involving a confirmed permanent partial disability with meaningful work restrictions often settle noticeably higher, and permanent total disability cases — where someone can no longer work in any capacity — can reach into the hundreds of thousands of dollars, with some catastrophic injury cases paid out over a lifetime. Several states also adjust their minimum and maximum benefit rates each year based on the state’s average weekly wage, so the specific dollar caps for 2026 differ from state to state.
How to Strengthen Your Case
A few practical steps tend to make the biggest difference once permanent restrictions are involved:
- Get restrictions in writing directly from your treating doctor or an independent medical examiner, not secondhand notes.
- Keep records of any wage difference between your old job and any new position you’re able to do.
- Document specific tasks you can no longer perform, not just a general description of pain.
- Avoid signing a full settlement release before you reach MMI, since this can lock in a lower number before the full extent of the restriction is known.
- Talk to a workers’ comp attorney in your state before accepting an offer, since the impairment-rating and wage-loss rules described above only apply correctly when applied under your specific state’s law.
How This Was Researched
I researched this topic using publicly available legal guides, state workers’ compensation statutes, and 2026 settlement-rate updates from several state agencies and law firm resources covering California, Virginia, Pennsylvania, and Illinois. Many existing articles on this topic focus on a single state or skip explaining when a restriction does not raise the settlement, so this guide tries to cover both sides and explain the general national principles alongside the state-by-state differences. Where a specific dollar figure or rule varies significantly by state, I’ve noted that instead of giving one fixed number.
FAQ
Does every permanent restriction increase my settlement?
Not automatically. It usually helps most when the restriction stops you from doing your old job or earning your old wage. A restriction that doesn’t affect your actual work may have little effect on the final number.
What’s the difference between temporary and permanent restrictions for settlement purposes?
Temporary restrictions apply while you’re still healing and mainly affect short-term wage benefits. Permanent restrictions are assigned after maximum medical improvement (MMI) and typically factor into your long-term disability rating and settlement value.
Do I need a lawyer to get a higher settlement with permanent restrictions?
It’s not required, but permanent restriction cases involve state-specific rating formulas that are easy to get wrong without legal help, so many injured workers use an attorney at this stage.
Can my employer or insurer dispute the permanent restriction?
Yes. Insurers can request an independent medical exam and may argue the restriction is less severe than your treating doctor states, which is why clear, consistent medical documentation matters.
Will accepting a settlement affect my future medical care?
In many states, a lump-sum settlement (sometimes called a compromise and release) closes out your right to future medical benefits for that injury, so this should be reviewed carefully before signing.
Accuracy Note:
This article is based on publicly available information, including state workers’ compensation statutes and law firm guides current as of 2026. Settlement rules and rates vary by state and can change; if you spot anything outdated or incorrect, please let us know so we can update it.
Written and researched by Ubaid, contributor at ybrmagazine.com.